




Winter Road Maintenance and Snow Removal Equipment: Market Outlook
The week a fleet manager sees the first salt-stained forecast is the week the winter road maintenance market stops being an abstract topic. Attachments are already mounted, operators are scheduled, and the only variable…
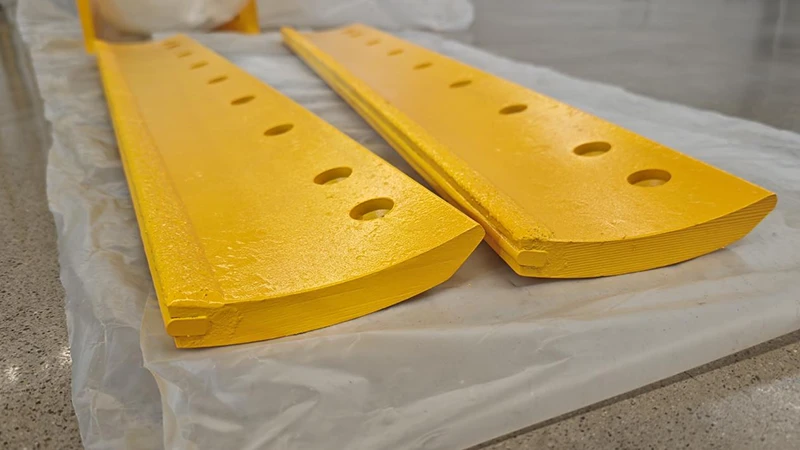
The week a fleet manager sees the first salt-stained forecast is the week the winter road maintenance market stops being an abstract topic. Attachments are already mounted, operators are scheduled, and the only variable left is whether the edges on the fleet will finish the season without an unscheduled change-out in a storm.
This outlook is written for that week. It covers what the published record shows about the winter road maintenance market, what is driving change in equipment and consumables, what it means for the buyers who run the fleet and the suppliers who build the parts, how regions differ, and what to watch over the next twelve months.
What the Data Shows
The public record is about practice, not about unit prices.
Citable sources describe how agencies plan and deploy winter operations, how weather varies, and what de-icing materials do to roads and runoff, rather than what an edge should cost.
The strongest published material on the operational side comes from national road programme guidance. The winter maintenance resources published by the FHWA road weather programme set out how agencies organise treatment, timing and performance measurement, which is useful when a fleet has to justify an equipment or consumables decision against a level-of-service target rather than against a purchase order.
State practice is the second layer. Agencies that publish their own winter operations material, such as MnDOT, show how specification and equipment choices are actually made where snow is routine: by route classification, by storm frequency and by the surface being treated. That is a better guide to buying behaviour than a market total.
The third layer is climate and materials. Seasonal variability, not the average winter, is what strains a budget, and the climate reference material published by NOAA is the honest place to start when a planner wants to know how much variation to expect. On the material side, de-icing salt guidance from the Salt Institute and the municipal stormwater programme material from the EPA explain the two constraints that shape treatment plans: what salt does to the road and what runoff does to the receiving water.
Nothing in that record gives a plausible market size. Where a research house publishes a winter maintenance total, it is an estimate for sale, not an operational figure, and it should never be presented as SENTHAI data or used as a planning input.
What Is Driving the Change
Service expectations are rising while crews stay flat.
Agencies are asked to clear more route miles to a tighter standard with roughly the same crew, so equipment uptime and consumable life carry more of the performance load.
The first driver is the level of service itself. Bare-pavement and similar targets convert into more passes, more aggressive blade angles and more contact pressure per route mile, and every one of those changes accelerates edge wear. A fleet that used to run a route twice now runs it three times, and consumable planning written under the old assumption undershoots.
The second driver is the shift from reactive ploughing to treated routes. Pre-treatment and brining require different timing, different material handling and different equipment duty, and they change the mix of surfaces an edge meets in a season: less clean snow, more packed ice, more refreeze. Packed ice is the condition that separates a general-purpose steel edge from a specified carbide edge, and it is why buyers increasingly ask about profile and grade instead of thickness alone.
The third driver is labour. Operator time is the most expensive line in winter operations, and it is the line a longer-wearing edge protects. When a change-out costs a crew hour, a slower-wearing consumable can be the cheapest option on the fleet even at a higher unit price, which is the arithmetic behind most carbide conversions.
The fourth driver is private capacity. Contracted operators influence what equipment a municipality can deploy at short notice, and the SIMA professional body material describes how that market organises itself around contracts and storm cycles.
What It Means for Buyers
Buy continuity and fitment, not a lower unit price.
Because a storm does not reschedule, the buyer’s real requirements are a validated bolt pattern, a documented grade and a supply line that holds across the season.
Start with fitment. A blade that does not match the moldboard and hole pattern is scrap on the yard, and the cheapest way to avoid that is to validate against a drawing or a physical sample rather than against a photograph. SENTHAI validates AASHTO and DIN bolt patterns that way, and the same discipline applies whether the buyer is a municipal fleet, a county, a DOT or a contractor running a mixed fleet of attachments.
Next, specify the surface. A route that is mostly fresh snow on asphalt and a route that is packed ice on a crowned road are not the same application, and the blade selection guidance exists precisely because the answer changes with the surface, the attachment and the wear pattern. Writing the surface into the specification is what makes a quotation comparable.
Then treat the season, not the order, as the unit of planning. Two change-outs at one price and four at a lower price are not equivalent, and the number that decides between them is cost per lane mile including change-out labour. Anything on volume band, packaging, sampling or delivery window is agreed per order and stated in the written quotation or order documents, so it can be compared like for like.
Finally, plan the spares position. Holding a second set of edges for the two busiest routes is cheaper than a mid-storm change-out, and it is a decision a buyer controls without asking a supplier for anything except a consistent part.

What It Means for Suppliers
Fitment data and seasonal continuity win winter programmes.
A supplier who can confirm a bolt pattern from a drawing and hold a supply line through a peak month is worth more than a discounted catalogue part.
Winter buyers are seasonal buyers, and seasonality concentrates risk into a few weeks. The suppliers who hold municipal and contractor business are the ones who can respond to an urgent enquiry with a fitment answer on the same call, then ship a part that matches the drawing. That capability comes from owning the process: powder preparation, pressing, sintering, induction brazing with annealing, vulcanization and finishing under one roof, supported by lot-level traceability so a batch can be identified after delivery.
Regional demand patterns shape the offer as much as the engineering does. A supplier to North American fleets has to work in AASHTO and DIN bolt patterns and in the sizes those attachments use; a supplier to European municipal fleets meets a standards-led technical file habit; a supplier to Middle East and Asian markets often faces mixed equipment fleets where the ability to supply edges, inserts and fasteners in one delivery matters more than a wide profile range.
Winter highway practice on the equipment side has moved toward telemetry, treated routes and tighter documentation, and suppliers who mirror that discipline in their own paperwork – grade records, dimensional reports, packing lists – spend less of the season answering queries and more of it producing.
Regional Differences
Winter is local, and so is the buying behaviour. Two agencies in adjacent states can run the same truck with different edge specifications, different salt strategies and different contract structures, and a supplier that treats North America as one market will misjudge all three.
In the northern United States and Canada, public agencies dominate, programme cycles are long, and material and edge specifications are copied between neighbouring agencies. That rewards suppliers who maintain a documented part range with validated bolt patterns. In Europe, municipal and national road authorities work to a standards-led file, which makes technical documentation the entry ticket. In the Middle East and parts of Asia, winter duty is concentrated in highland and specific corridors, so orders are smaller and more mixed, and responsiveness counts for more than breadth of catalogue.
Climate variation cuts across all of it. A region with reliable snow plans differently from a region that gets one severe event a decade, and the second type of region is where a fleet is most likely to be caught with the wrong consumable stock. That is a planning difference, not an engineering one, and it is better handled by sizing the spares position around the severe case rather than the average.
What to Watch Over the Next 12 Months
Watch treatment practice and crew capacity, not market totals.
The changes most likely to affect what a fleet buys are shifts in route treatment practice, staffing pressure and the documentation agencies attach to winter contracts.
Watch the treatment mix. If an agency moves further toward pre-treatment or brining, the wear profile on the fleet changes, and edges bought for clean snow duty may not be the right ones. Watch the level-of-service language in the next round of programme documents, because a stricter target converts directly into extra passes and a faster wear cycle.
Watch staffing. Where a fleet cannot fill operator positions, it runs fewer machines longer, which increases the value of a consumable that carries a route without a change-out. Watch the contract terms agencies attach to winter work, including evidence and reporting requirements; those filter down to consumable suppliers as documentation demands.
Finally, watch the runoff side. Stormwater programme expectations continue to shape how much salt a route can carry, and a lighter salt strategy means the blade does more of the work. Neither trend needs a market forecast to act on: both show up in a specification, and a specification is something a buyer can write this quarter.
How to Act on This
Rewrite the specification before the season, not during it.
Convert the outlook into a route-by-route consumable plan, a fitment check on every attachment, and a spares position sized for a severe winter.
- Classify routes by surface and treatment method, then list the wear condition each one imposes on an edge.
- Audit every attachment: moldboard, bolt pattern, hole spacing and current edge dimensions, recorded against a drawing or a measured sample.
- Specify the consumable by grade, profile and tolerance, and ask each supplier for the same evidence package.
- Model the season on cost per lane mile including change-out labour, not on unit price.
- Set the spares position against the severe winter case, and confirm continuity terms in writing before the first forecast.
If a route is still eating edges twice against the plan, that is a specification question rather than a purchasing question, and it is the right moment to involve the manufacturer rather than the catalogue.
The winter road maintenance market is most clearly read through practice rather than through a market total. Level of service, treatment mix, staffing and runoff rules all push the same way: toward fewer change-outs, validated fitment and documented grade. A buyer who classifies routes, audits attachments and compares on cost per lane mile gets a defensible consumable plan; a supplier who can answer a fitment question with a drawing and a grade question with a record gets the programme. Commercial terms stay where they can be checked, in the written quotation or order documents.
Send SENTHAI your attachment details, hole spacing and route conditions, and the technical team will review edge profile, grade and bolt pattern fitment against your fleet before quoting.
Frequently Asked Questions
What should a fleet hedge first if the winter is worse than forecast?
Hedge the parts that stop a route, not the whole inventory. A second set of edges for the highest-duty routes and a confirmed fitment record for every attachment cover most of the risk, and both are decisions the fleet controls. Anything about volume bands, delivery windows or standing stock belongs in the written quotation or order documents so it can be checked.
How does edge choice change a winter operations budget line?
It changes the number of change-outs, which is where labour and downtime accumulate. A longer-wearing specified edge reduces the frequency of the most expensive event in the season. The comparison only becomes meaningful when it is made on cost per lane mile including change-out labour, using each supplier’s documented terms rather than unit prices alone.
Do we need carbide edges on every route?
No. Carbide earns its place where the surface is packed ice, refrozen slush or abrasive aggregate, and where a change-out is expensive. On light snow duty over smooth pavement a conventional edge can be the more economical choice. Route-by-route classification, not a fleet-wide policy, is what produces a defensible specification.
What documentation should accompany a winter maintenance consumables order?
At minimum a grade statement with the test method, a hardness and grain size record, a dimensional report against the drawing, and a traceability reference for the lot. Ask for the same package from every supplier so the bids are comparable, and confirm that the same package travels with each delivery during the season.
{
“@context”: “https://schema.org”,
“@type”: “FAQPage”,
“mainEntity”: [
{
“@type”: “Question”,
“name”: “What should a fleet hedge first if the winter is worse than forecast?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “Hedge the parts that stop a route, not the whole inventory. A second set of edges for the highest-duty routes and a confirmed fitment record for every attachment cover most of the risk, and both are decisions the fleet controls. Anything about volume bands, delivery windows or standing stock belongs in the written quotation or order documents so it can be checked.”
}
},
{
“@type”: “Question”,
“name”: “How does edge choice change a winter operations budget line?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “It changes the number of change-outs, which is where labour and downtime accumulate. A longer-wearing specified edge reduces the frequency of the most expensive event in the season. The comparison only becomes meaningful when it is made on cost per lane mile including change-out labour, using each supplier’s documented terms rather than unit prices alone.”
}
},
{
“@type”: “Question”,
“name”: “Do we need carbide edges on every route?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “No. Carbide earns its place where the surface is packed ice, refrozen slush or abrasive aggregate, and where a change-out is expensive. On light snow duty over smooth pavement a conventional edge can be the more economical choice. Route-by-route classification, not a fleet-wide policy, is what produces a defensible specification.”
}
},
{
“@type”: “Question”,
“name”: “What documentation should accompany a winter maintenance consumables order?”,
“acceptedAnswer”: {
“@type”: “Answer”,
“text”: “At minimum a grade statement with the test method, a hardness and grain size record, a dimensional report against the drawing, and a traceability reference for the lot. Ask for the same package from every supplier so the bids are comparable, and confirm that the same package travels with each delivery during the season.”
}
}
]
}
